


Since 2007, the platform has used identity and payment controls to maintain transparent betting operations. More than 400,000 registered users and over 250 supported payment systems generate substantial account activity that requires structured supervision. AML procedures identify questionable financial behaviour, while KYC checks link each profile to a real person. For Nigerian players, these measures reduce the risk of stolen payment data, duplicate registrations and withdrawals initiated by unauthorised parties.
Customer Identity Verification Process
Personal details entered during registration must correspond to the individual who controls the account. A check may start after sign-up, before a payout or when unusual activity requires closer examination. The evidence requested depends on the payment channel, previous transactions and the assigned risk category.
| Verification item | Information checked | Main purpose |
| Identity document | Full name, date of birth, photograph and expiry date | Confirms identity and legal age |
| Address evidence | Name, residential address and issue date | Verifies the declared residence |
| Payment ownership | Card, wallet or bank account details | Detects third-party funding |
| Account activity | Deposits, bets and withdrawal requests | Reveals financial inconsistencies |
Every submitted image should be clear enough to read and display all necessary fields. Cropped photographs, edited records or details that conflict with the registered profile can result in a replacement request. The 1xBet Online Casino may require a newer document when the original version has expired.
Passing the initial check does not prevent later reviews. Significant changes in personal information, payment habits or device access may produce another request. Repeated verification helps protect the registered owner and keeps the payout route connected to a confirmed recipient.
Risk Assessment Protocols
Each account receives a level of scrutiny based on its identity data and financial behaviour. An individual deposit is not automatically regarded as suspicious. The review instead compares payment ownership, transaction size and previous activity to identify departures from the usual pattern.
Indicators that can raise the risk rating include:
- several profiles linked to one person, device or payment instrument;
- withdrawal requests made soon after deposits with minimal betting;
- repeated alterations to personal or financial information;
- funding through a card or wallet owned by another person;
- access from unexpected locations within a short period;
- payment amounts substantially above the account’s normal range.
A single warning sign does not establish misconduct. Compliance specialists can examine several connected events before delaying a transaction or requesting supporting evidence. Automated detection processes large volumes of activity, while manual assessment provides context for cases that cannot be decided from numerical patterns alone.
Ratings remain adjustable throughout the account’s lifetime. An unexplained increase in payment frequency may result in tighter controls, whereas valid documents can resolve an existing alert. This approach allows 1xBet to concentrate additional checks on cases involving greater financial exposure.
1xBet Transaction Monitoring
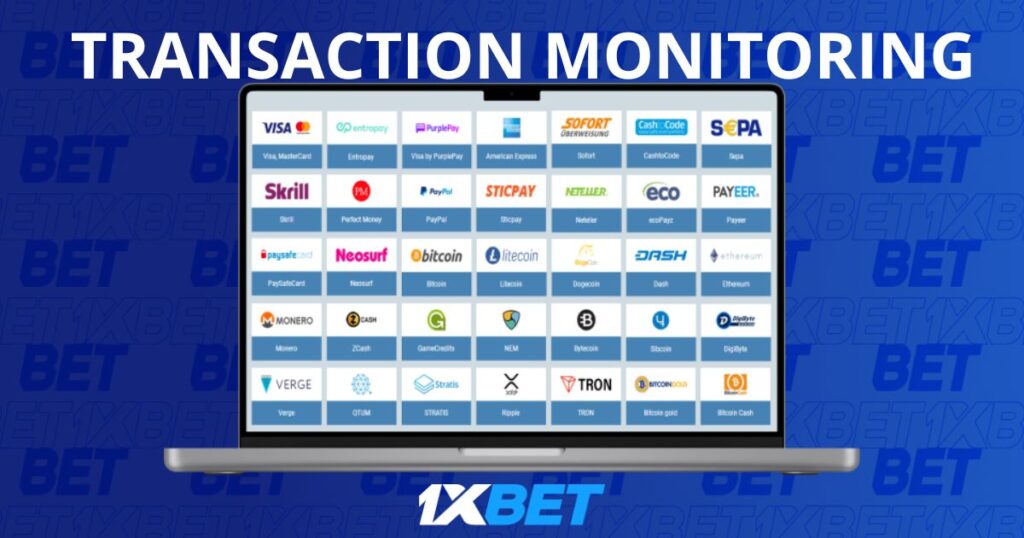
Financial activity is examined from the initial deposit to the final withdrawal. With more than 250 supported payment systems, uniform controls are necessary for bank cards, electronic wallets and other cashier options. The methods shown and their conditions can vary according to the Nigerian profile and selected transaction channel.
| Observed pattern | Possible concern | Typical control |
| Deposit followed quickly by withdrawal | Account used mainly to transfer money | Transaction delayed for examination |
| Numerous failed payment attempts | Incorrect or unauthorised details | Ownership confirmation |
| Sharp increase in transaction value | Activity outside the normal range | Source-of-funds evidence |
| Use of several funding instruments | Third-party financing | Additional document request |
| Attempted change of payout route | Transfer to an unrelated recipient | Use of the original method |
Payouts are generally returned through the channel used to fund the balance. A matching route leaves a clearer transaction record and limits efforts to direct money to an unrelated card or wallet. If the original instrument cannot accept funds, the cashier or support service may identify a different option registered to the same customer.
Checks continue after the account holder has passed KYC because the two procedures address separate risks. One confirms who controls the profile; the other examines how money is deposited, used and withdrawn. Ongoing supervision can therefore reveal financial behaviour that was not present during registration.
Customer Due Diligence Standards
Account information is compared with the expected purpose and financial scale of its use. Standard examination usually covers the registered name, age, residential address and ownership of the chosen payment instrument. Cases assigned a higher rating can require stronger evidence before access to a transaction is restored.
An extended examination may involve:
- a valid identity record when the earlier document has expired;
- evidence explaining where deposited money originated;
- confirmation that the card, bank account or wallet belongs to the player;
- clarification of exceptionally large or frequent transfers;
- supporting records for recent changes to personal information;
- a replacement photograph when the first upload cannot be read.
Complete, original files help prevent avoidable delays. Names, dates and addresses should agree with the details saved in the profile. Sensitive fields may be concealed only when the upload instructions expressly allow it. Accepted formats and maximum file sizes should be confirmed on the relevant submission screen.
Payment functions can remain temporarily unavailable while the Online Casino examines unresolved information. Such a limitation does not independently prove that a rule was broken. It preserves the financial record until specialists establish the customer’s identity, ownership of the payment method and legitimate origin of the money.
Global Sanctions Screening
Provided identity details are compared with Nigerian and international restriction records. Reviews may also reveal politically exposed persons, recognised aliases or parties associated with financial crime. This layer of AML control limits the ability of prohibited individuals and organisations to use betting accounts for transferring funds.
Information examined can include:
- the customer’s full legal name and alternative spellings;
- date of birth and nationality recorded during verification;
- possible links to politically exposed persons or close associates;
- entries related to financial restrictions or criminal enquiries;
- recent watchlist additions affecting an established profile.
Matching names alone are insufficient to confirm a restricted party. Specialists can use birth dates, nationality and other identifiers to distinguish the customer from somebody with similar details. This comparison is particularly important for common names that have several accepted spellings or transliterations.
New alerts may appear long after registration because official lists change over time. An alert can lead to a document request, a delayed transfer or a temporary access limitation. When available evidence confirms a prohibited connection, 1xBet may decline the payment or suspend the profile. An incorrect match can be cleared once the identifying information has been examined.